Nubank, Latin America's largest digital bank, has launched Nu Global: a multi-currency account that quietly places stablecoins at the heart of everyday banking for millions of users who may never realize it. The announcement came alongside the company's official expansion into the United States, connecting more than 35 countries across Latin America and Europe, with fee-free international transfers powered by stablecoins. The technical engine running underneath is a pair of well-established stablecoins, USDC and EURC, both issued by Circle and pegged one-to-one to their respective fiat currencies.
What's striking here isn't that a digital bank has added crypto to its product lineup. That's routine now. What's different is the direction of the integration: stablecoins are not being offered as a product users consciously choose. They're the hidden infrastructure making a familiar banking service work. Here's how Nu Global actually functions, and what every potential user should know before depositing serious money.
How Nu Global Works
The mechanics are conceptually straightforward. When a customer deposits money into a Nu Global account, the funds are automatically converted into one of two stablecoins: USDC for dollar balances or EURC for euro balances. From that point, the user can send and receive money across 35-plus countries, with the initial focus on routes between Europe and Latin America, and a planned extension to Brazil, Colombia, Mexico, and the United States. The account also bundles a virtual Mastercard and the ability to hold and trade a selected set of cryptocurrencies, including Bitcoin and Ethereum, directly within the app.
Featured in @FintechCH: @nubank, the largest digital bank in Latin America, partners with Sygnum Bank to launch Nu Global.
— Sygnum Bank (@sygnumofficial) September 11, 2026
"Nu Global is a new high-yield account that holds several currencies. It offers fast, free transfers to more than 35 countries," writes the Fintechnews… pic.twitter.com/TiSqtLBVEV
For the end user, the entire technological stack beneath, the wallets, the blockchain rails, the conversion mechanisms, stays completely invisible. What appears on screen is simply a currency account that moves money quickly and without service fees across borders: a promise that has historically taken days and carried steep charges through traditional bank wires.
 chaian.raiadnubank.com.br
Two Important Caveats Before Getting Excited
Two technical details deserve serious attention. The first concerns the advertised yields for customers who maintain a balance: 3.50% annually on dollar balances and 2.20% on euro balances, according to Nu Holdings' official announcement. Nubank has not specified where exactly this return comes from: whether it flows from incentives provided by Circle as the stablecoin issuer, from income generated by the reserve assets backing USDC and EURC, from lending activity, or from a direct subsidy paid by the company itself. That distinction matters considerably. A yield on a stablecoin can carry a very different risk profile from interest on a traditional bank deposit covered by a government-backed deposit guarantee scheme like FDIC protection in the United States.
The second caveat concerns the legal structure of the product. Precision here is essential to avoid dangerous misunderstandings. Nubank's new US bank account and the Nu Global account are two legally distinct instruments. The American banking operations run through a partner institution insured by the FDIC. Nu Global, by contrast, operates through a separate entity operating under a Swiss regulatory framework. Converts received funds into stablecoins. Users of Nu Global do not necessarily enjoy the same protections that apply to a standard insured bank account. That's a detail every prospective user should understand clearly before depositing meaningful sums.
Nu Global: Key Numbers
Facts and caveats. Source: Nu Holdings, 2026
- The reach: 35+ countries connected, with fee-free international transfers.
- The yield: 3.50% on USDC balances, 2.20% on EURC balances, but the source of that return is undisclosed.
- The caveat: Swiss legal structure, not equivalent to an FDIC-insured bank deposit.
Not a Niche Experiment: A Platform for 140 Million Customers
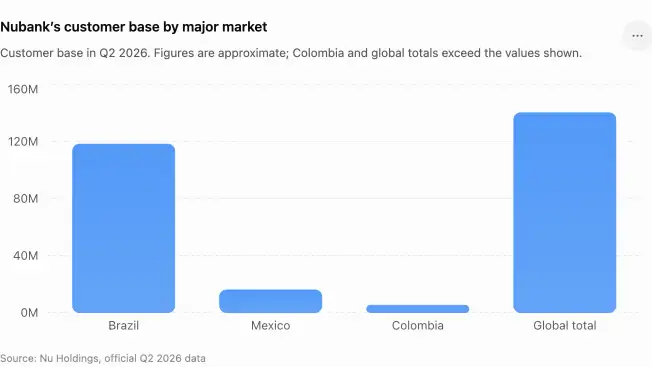
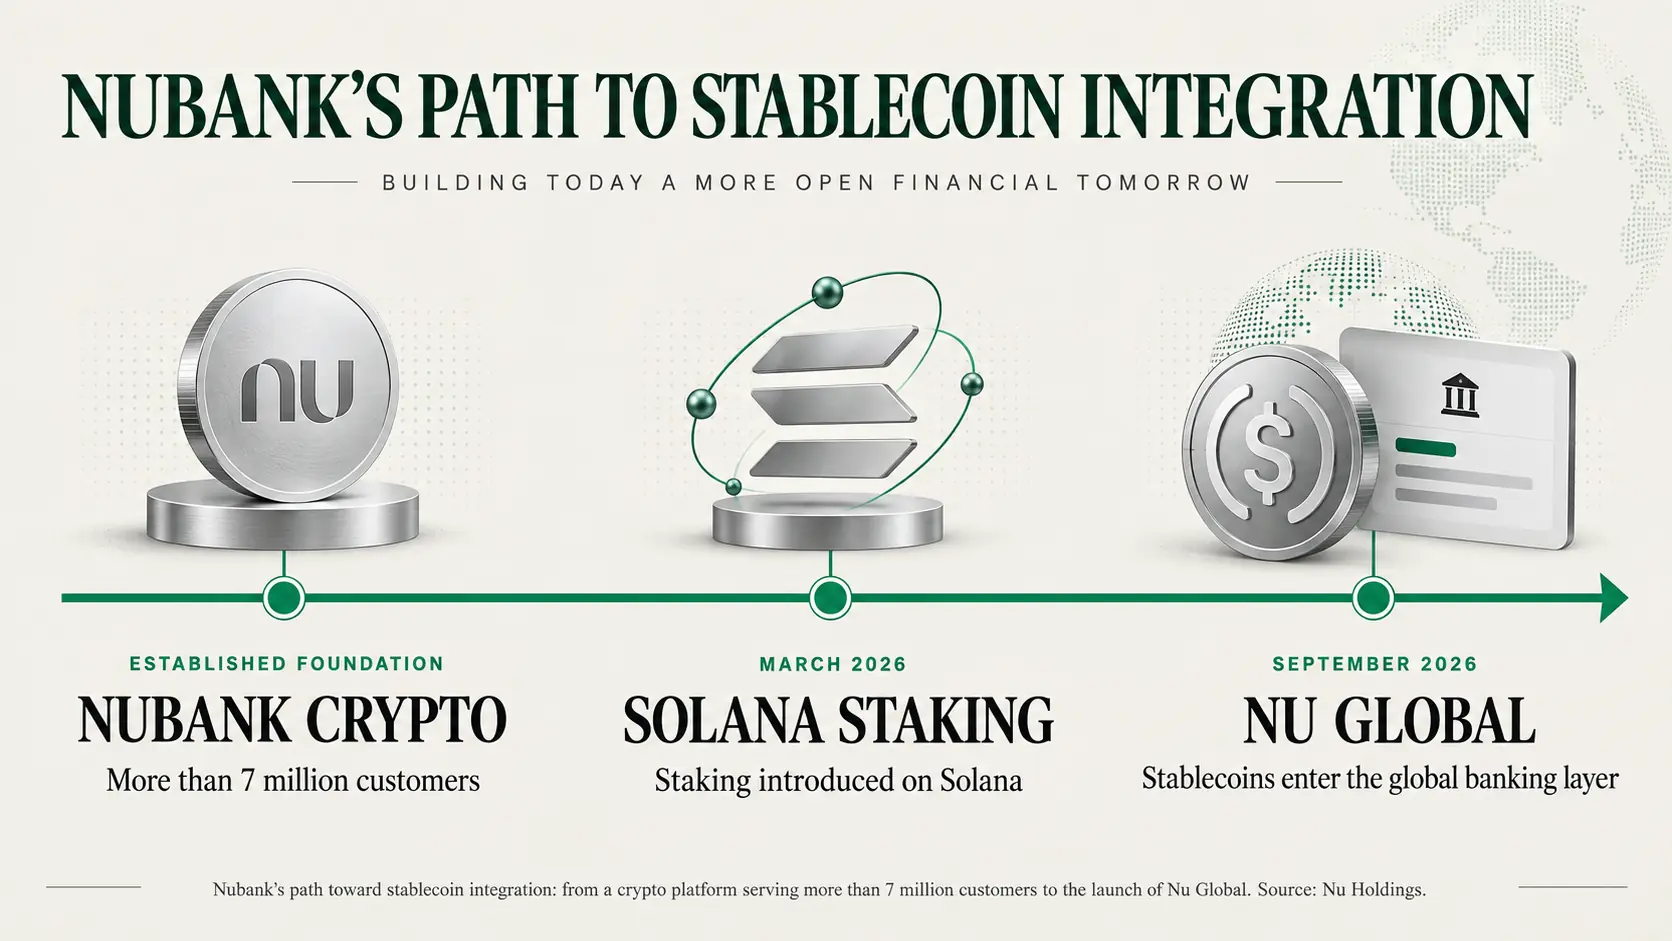
What makes this move significant is the scale of the company behind it. Nubank is not starting from scratch in crypto: its dedicated crypto platform, active in Brazil, already serves over 7 million customers, and since March 2026 it has also offered Solana staking. The broader group reported more than 140 million customers globally at the end of Q2 2026, with a record net profit exceeding $1 billion, according to the company's SEC filing, making it the first quarter in its history to cross that threshold.
To put the territorial footprint in perspective: approximately 118 million of those customers are in Brazil alone, nearly 16 million in Mexico, and over 5 million in Colombia. Nu Global is not a pilot for tech-savvy early adopters. From launch, it's infrastructure aimed at tens of millions of people who have likely never owned a stablecoin and will never need to understand what one is. The same underlying principle appeared when Lisk restructured itself as a fintech platform that conceals the blockchain layer from end users, and it aligns with the direction taken by large payment networks such as Visa with its stablecoin-based lending model.

The Bigger Picture: Invisible Adoption
Nu Global may represent one of the most consequential cases of silent stablecoin adoption seen to date, for a precise reason: it asks users to do nothing different from what they already do with any other bank account. There's no wallet to configure, no recovery phrase to memorize, no need to know what a blockchain is. There's just an account that works, and works well, for moving money around the world. That's the exact opposite of how the crypto industry has typically presented itself, built on technical terminology and a certain pride in staying distinct from traditional finance.
The lesson here is twofold. On one hand, cases like this suggest that the broadest adoption of stablecoins may arrive precisely when they stop being perceived as stablecoins at all, becoming simply the invisible infrastructure beneath otherwise familiar financial services. This connects to a broader pattern, including the growing role of digital euro initiatives within European banking consortia. On the other hand, because this integration becomes invisible, the responsibility on builders to communicate clearly about yield sources and legal protections grows accordingly. As this case shows, those two elements are not yet fully transparent. Technological invisibility should never become opacity on the information that genuinely matters to people entrusting their savings to a service. For a clearer grounding in these instruments, our guide on what stablecoins are and how they work remains a useful starting point.